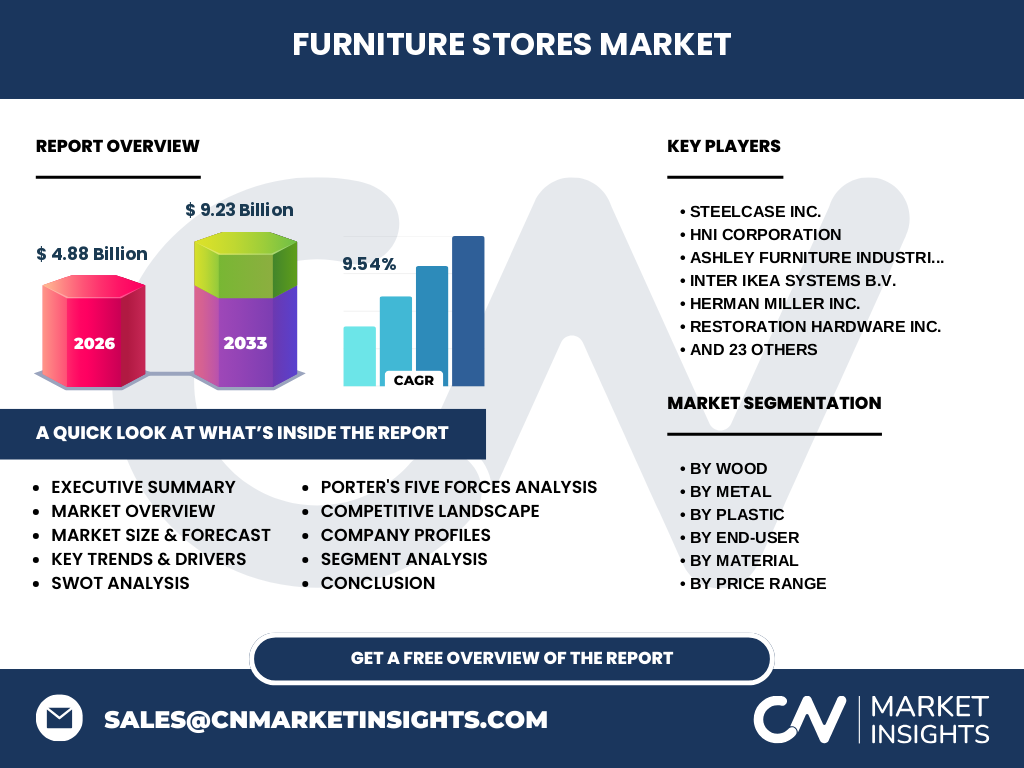
Market overview of the Furniture Stores Market
Our analysis indicates the Furniture Stores Market reaches a valuation of $4.88 Billion in 2026. This foundational sector encompasses commercial retail establishments offering durable and aesthetic interior furnishings. Industry significance is anchored in supply chains dealing with raw materials like solid wood, steel, and polyurethane.
Key market drivers, restraints, challenges, and opportunities shaping the industry
Growth is propelled by urbanization and commercial real estate buildouts, though constrained by volatile lumber tariffs and maritime shipping bottlenecks. Opportunities lie in integrating augmented reality visualization tools across home centers and specialty stores to reduce high return rates.
Emerging trends and growth patterns in the Furniture Stores Market
The shift toward sustainable living has accelerated consumer preference for reclaimed wood and recycled aluminum frames. Retailers specializing in eco-certified inventory are capturing higher market share among younger demographic cohorts.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions severely impacted brick-and-mortar storefronts like La-Z-Boy Inc. and Ethan Allen Interiors Inc. However, the subsequent recovery trajectory was defined by an unprecedented surge in remote work residential remodeling investments.
Competitive landscape and strategic market concentration
The market features intense rivalry between multinational giants like Inter IKEA Systems B.V. and domestic powerhouses such as Ashley Furniture Industries Inc. Market concentration is moderately fragmented, with regional players competing fiercely against e-commerce pure-plays.
Executive summary of the Furniture Stores Market industry trends
Driven by robust lifestyle shifts, the market is poised to expand from $4.88 Billion in 2026 to $9.23 Billion by 2033 at a CAGR of 9.54%. Strategic agility in omnichannel distribution remains the primary differentiator for top-tier market participants.
Market forecast from 2027 to 2033
Based on our research, the sector will experience accelerated momentum, projecting an impressive compound annual growth rate of 9.54% to reach $9.23 Billion by 2033. This expansion is underpinned by rising disposable incomes and commercial office retrofits.
Segmentation analysis by material, price, and channel
Segmentation spans wood, metal, and plastic materials, alongside high-end, medium, and low price ranges. Distribution occurs through home centers, flagship stores, and online platforms. Engineered wood and medium-priced residential segments dominate volume consumption.
Regional market analysis and geographic distribution
Geographic performance varies, with North America leading in retail density, while Asia-Pacific exhibits the fastest adoption of automated manufacturing. Localized compliance with formaldehyde emission standards heavily influences regional supply chain strategies.
In-depth regional review of key markets
North American urban centers demand versatile, space-saving designs, whereas European markets prioritize strict circular economy mandates. Logistics hubs near major ports facilitate efficient cross-border movement for conglomerates like Berkshire Hathaway Inc.
Company profiles and strategic positioning of leading enterprises
Key entities like Steelcase Inc. and Herman Miller Inc. dominate the commercial office sector, while Rooms To Go Inc. and Bob's Discount Furniture LLC capture high-volume residential demand through aggressive promotional financing and localized warehousing.
Porter's Five Forces analysis of competitive intensity
Bargaining power of suppliers remains moderate due to diverse material inputs like PVC and rattan, while threat of substitutes is low. High capital requirements for physical flagships temper the threat of new entrants.
SWOT analysis of the Furniture Stores Market
Strengths include robust omnichannel infrastructure; weaknesses involve high inventory holding costs. Opportunities center on modular office systems for hybrid workspaces, while threats stem from raw material price volatility and regulatory scrutiny.
Value chain analysis from raw materials to end-users
The value chain initiates with timber harvesting and metal extraction, flowing through tier-one component manufacturers, assembly plants, and finally to flagship showrooms or home centers serving residential and hotel clients.
Investment insights and high-potential areas
Investors should target direct-to-consumer digital platforms and sustainable material innovators utilizing recycled polycarbonate and aluminum. High-end ergonomic office furniture manufacturers also present strong margin expansion potential.
Conclusion and key takeaways for industry stakeholders
Navigating the projected path to $9.23 Billion requires balancing digital transformation with agile physical retail footprints. Companies embracing supply chain transparency will outperform peers.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registries, primary stakeholder interviews with executives from Williams-Sonoma Inc. and La-Z-Boy Inc., and secondary macroeconomic indicators from global trade bodies.
Scope of the report and coverage parameters
This report evaluates the global Furniture Stores Market across specified material, price, and channel parameters from 2026 through 2033. Regional limitations exclude informal grey-market transactions lacking formal trade documentation.
Recent developments, partnerships, and product launches
Recent strategic moves feature major investments in automated warehouse robotics by industry leaders and sustainability-focused product launches utilizing reclaimed wood. Strategic mergers continue to consolidate regional retail footprints across North America.